20+ banks and NBFCs compared
Home purchase loan
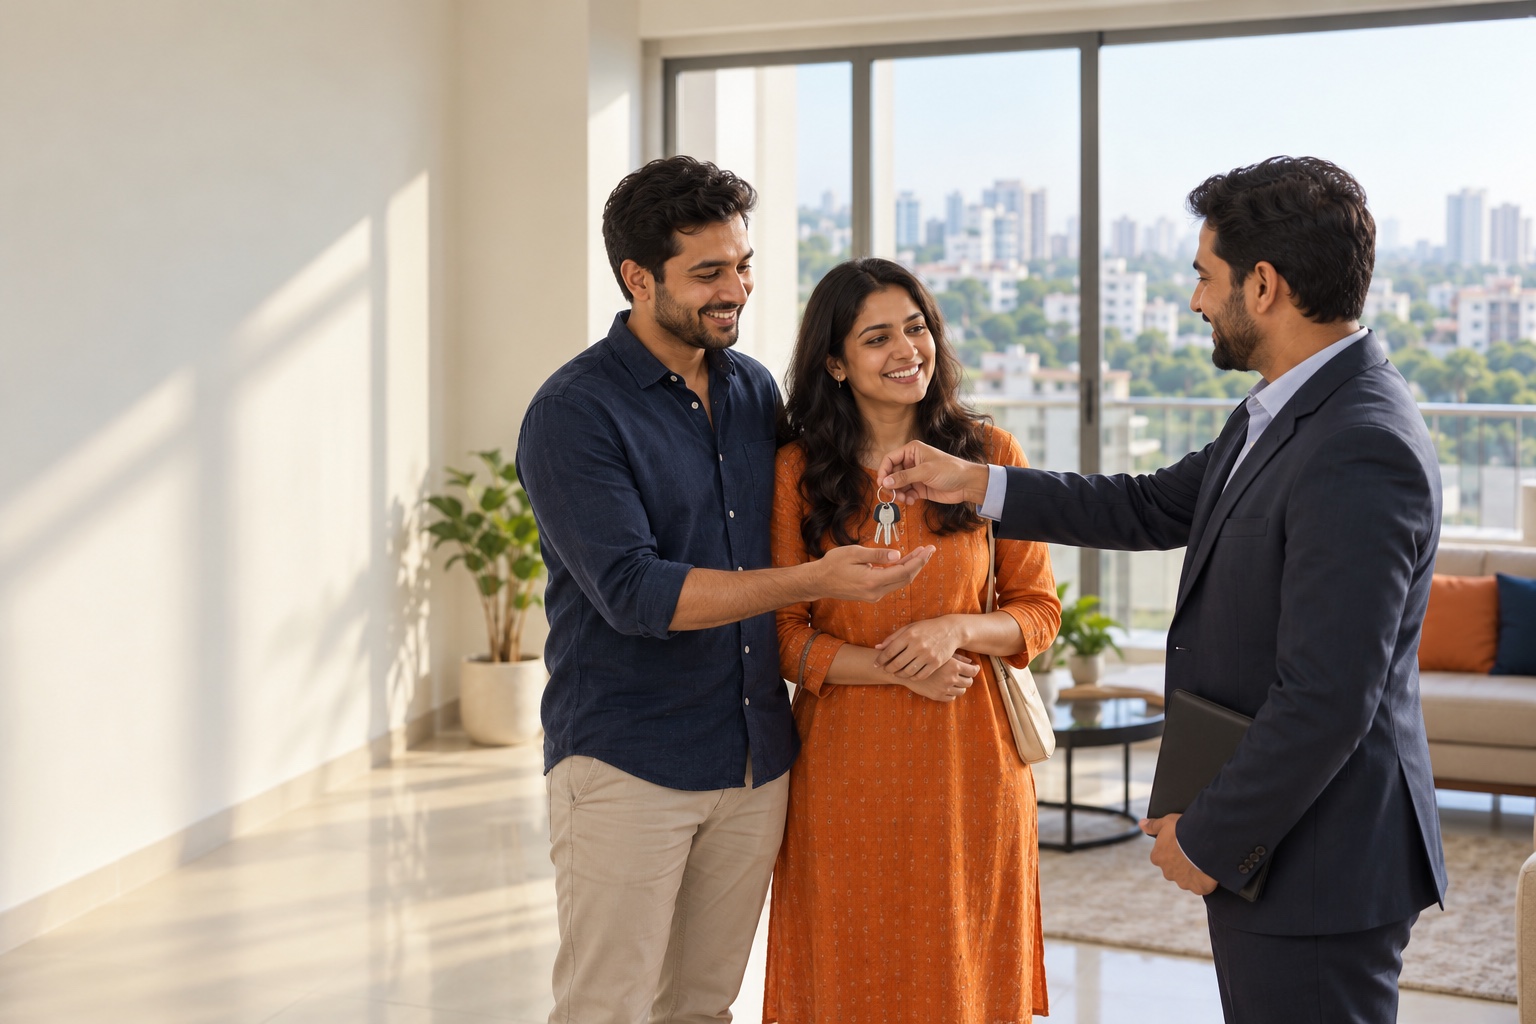
Buy a ready flat, villa or independent house anywhere in Bengaluru.
Mon–Sun 10 AM – 7 PM
WhatsApp (opens in a new tab)Free home loan advice · Bengaluru
Many banks turn these properties down. We know which of 20+ banks and NBFCs lend on your type of Khata, prepare your file, and stay with you until the loan is disbursed. Free for you.
Takes under a minute. Our expert calls you back, 10 AM – 7 PM, all 7 days. No charge from us; lenders charge their own fees.
“No bank was ready to provide loan…”
Free callback
Tell us a little about your loan. We'll call you back during office hours, all 7 days, and tell you which lenders suit your property.
Our expert calls you back.
During office hours, 10 AM – 7 PM, all 7 days.
Free check of your case.
We look at your income, credit and property papers, and tell you honestly what is possible.
You get your lender options.
We shortlist lenders that suit your property and compare rates and charges with you.
We are a home loan advisor, not a lender, so the final decision on your loan is always the lender's.
and more, 20+ banks and NBFCs in all.
Lender names are shown to identify the lenders we compare. We are not a lender, and this is not a statement of partnership.
Loans we arrange
Buying, building, moving your loan or raising funds against your property. We compare lenders for each.
Buy a ready flat, villa or independent house anywhere in Bengaluru.
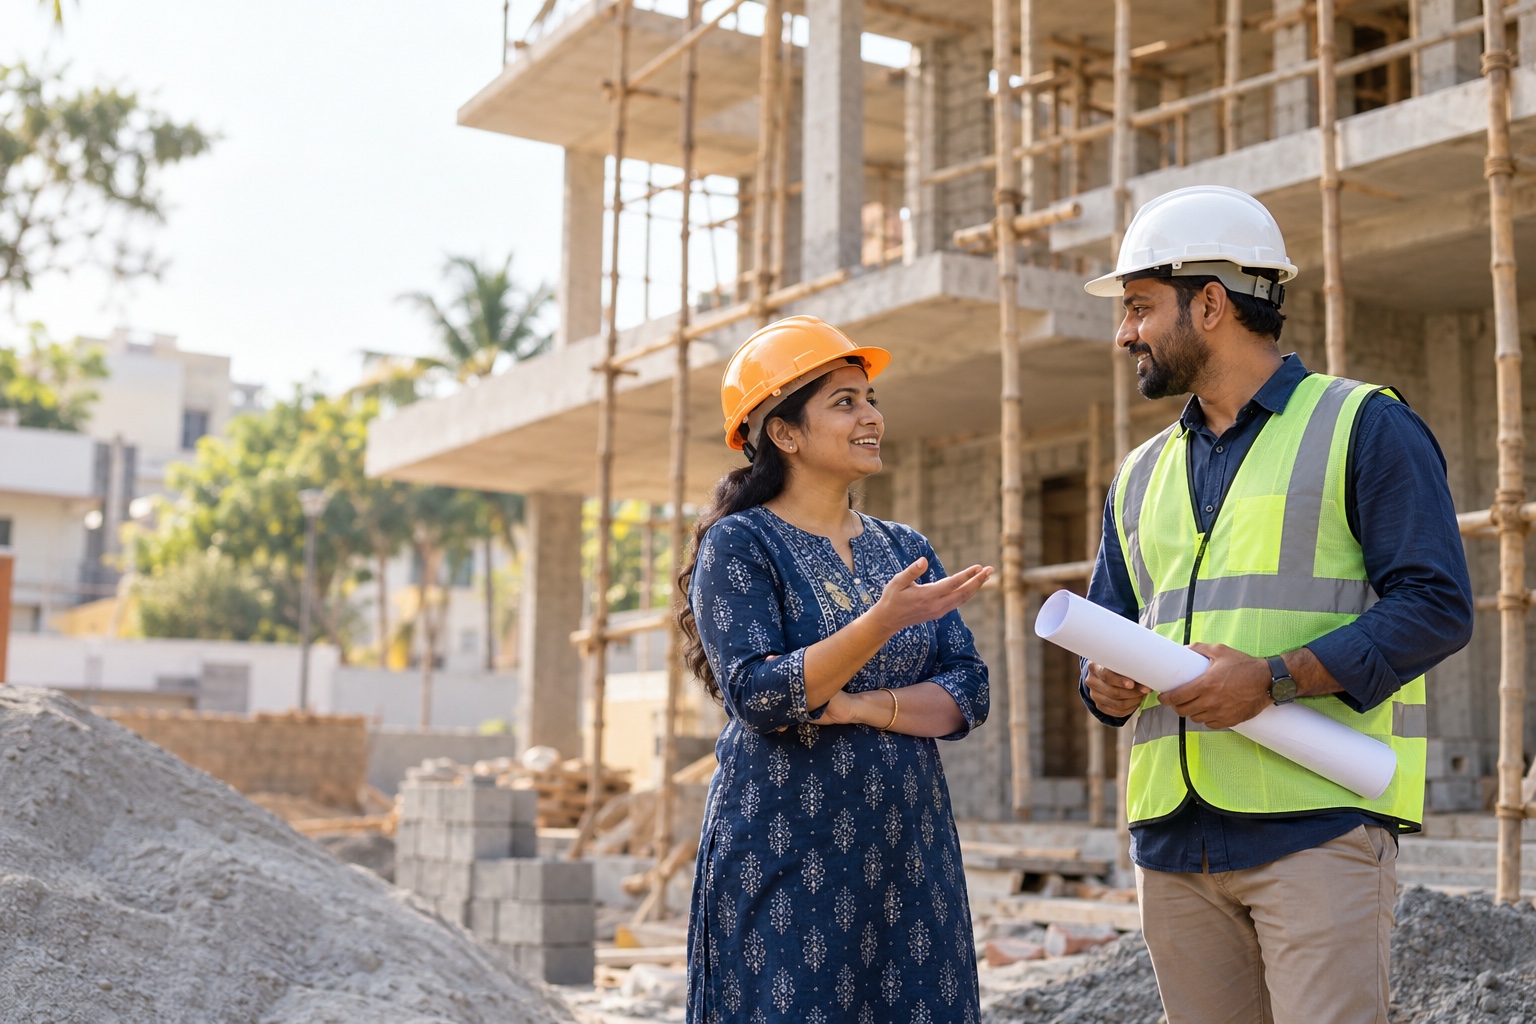
Build on land you own, with funds released stage by stage.
Buy or build in Bengaluru while you live and work abroad.
Move your existing home loan to a lender with a lower rate, if the savings beat the charges.
Buy a site and build your home with one loan.
Buy an approved residential site for your future home.
Raise funds for business or personal needs against property you own.
Renovate, extend or repair your home.
Extra funds on your current home loan, usually at a lower rate than a personal loan.
Our speciality
A “no” from one bank is not the final answer. Each bank, NBFC and housing finance company has its own rules for B Khata, E Khata, Manual Khata and Panchayat properties. Some lend on them, often with stricter document checks or a lower loan amount than for an A Khata property. We know which lenders consider which property types, what papers they ask for, and how to put your file together so it is judged on its merits.
We read your papers first. Khata certificate and extract, sale deed, EC and tax receipts, before any application goes in.
We approach the right lenders. Only lenders that consider your Khata type, so you don't collect needless rejections.
We coordinate legal and valuation. We work with the lender's lawyer and valuer so checks don't stall your file.
A Khata? A fully approved property usually has the widest choice of lenders.
| Lender | Interest rate (p.a.) | Loan amount | Max tenure |
|---|---|---|---|
| ICICI Bank | 7.5% – 8% | ₹5 lakh – ₹10 crore | 30 years |
| Axis Bank | 7.5% – 8% | ₹10 lakh – ₹10 crore | 25 years |
| LIC Housing Finance | 7.4% – 8% | ₹5 lakh – ₹10 crore | 30 years |
| Aadhar Housing Finance | 7.5% – 8% | ₹5 lakh – ₹10 crore | 30 years |
| Jio Financial Services | 7.95% | ₹5 lakh – ₹10 crore | 30 years |
| PNB Housing Finance | 8.5% | ₹5 lakh – ₹10 crore | 30 years |
| Bajaj Housing Finance | 8.5% | ₹5 lakh – ₹10 crore | 30 years |
Indicative ranges. Your final rate depends on your income, credit score, property and lender approval. Not an offer of credit. Last reviewed: Awaiting review.
Areas we cover
Find lenders and local guidance for your part of Bengaluru.
Your area not listed?
Ask our expertCompare lenders
These are indicative starting ranges at lenders we compare. Your actual rate depends on your income, credit score, property type and the lender’s approval. We check today’s offers for your profile before you apply.
Buying a B Khata property? See B Khata rates
| Lender | Interest rate (p.a.) | Loan amount | Max tenure |
|---|---|---|---|
| State Bank of India | 7.2% – 7.8% | ₹5 lakh – ₹10 crore | 30 years |
| HDFC Bank | 7.2% – 7.8% | ₹5 lakh – ₹10 crore | 30 years |
| ICICI Bank | 7.2% – 7.8% | ₹5 lakh – ₹10 crore | 30 years |
| Axis Bank | 7.2% – 7.8% | ₹10 lakh – ₹10 crore | 25 years |
| Kotak Mahindra Bank | 7.2% – 7.8% | ₹10 lakh – ₹10 crore | 30 years |
| LIC Housing Finance | 7.2% – 7.8% | ₹5 lakh – ₹10 crore | 30 years |
| Punjab National Bank | 7.2% – 7.8% | ₹5 lakh – ₹10 crore | 30 years |
| Indian Bank | 7.2% – 7.8% | ₹5 lakh – ₹10 crore | 30 years |
| Bandhan Bank | 7.5% – 7.85% | ₹5 lakh – ₹10 crore | 30 years |
Indicative ranges. Your final rate depends on your income, credit score, property and lender approval. Not an offer of credit. Last reviewed: Awaiting review.
Rates are indicative and change often. They are not an offer or a guarantee. Lenders decide the final rate, loan amount and terms. Housing Loan in Bangalore is a loan advisor, not a lender.
Why choose us
Powered by Profit Tantra Financial Services LLP, part of the Profit Tantra Group.
Instead of visiting bank after bank, you speak to one expert who compares banks, NBFCs and housing finance companies for you.
Our advice and file support carry no advisory fee, from the first eligibility check to disbursal. Lenders still charge their own processing, legal and valuation fees, and we explain these upfront.
We give you a checklist for your case, check your documents and prepare a complete file before it goes to the lender.
We work with the lender's lawyer and valuer so their checks don't hold your loan up.
We follow through to disbursal and help with registration‑day paperwork at the sub‑registrar office.
No. 62, The High Street, 11th Main Road, Jayanagar 4th Block. Open all 7 days, 10 AM – 7 PM.
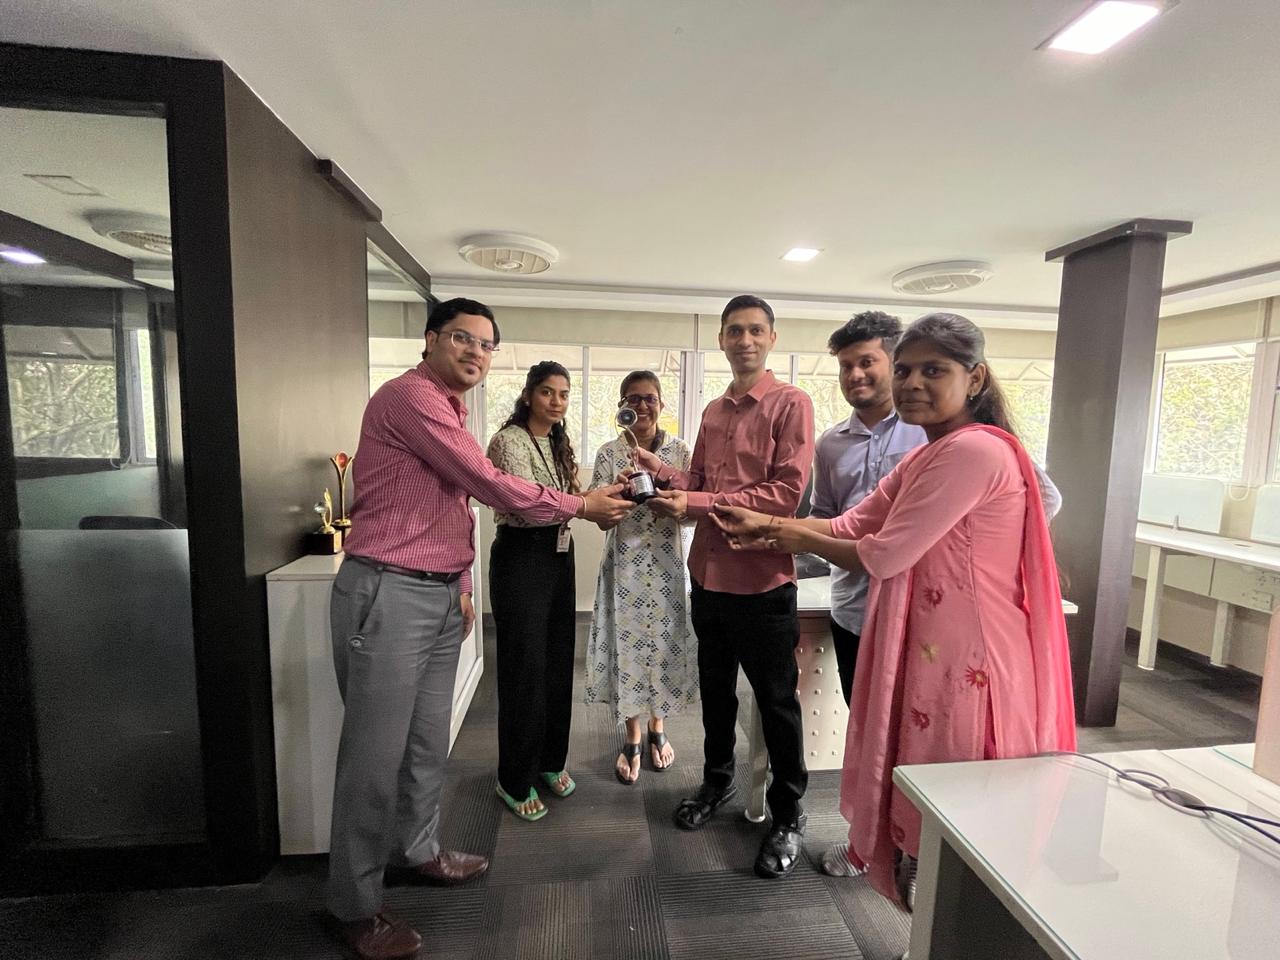
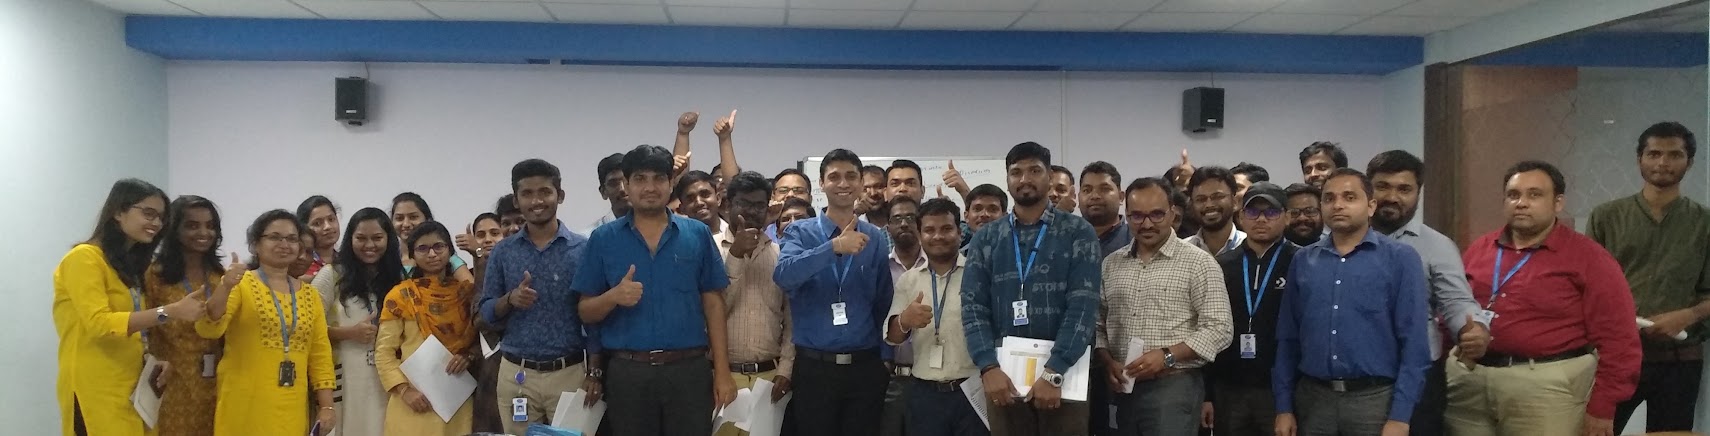
Recognition
A few moments from award stages and our office, with the team that works on your home loan file.
Tap a photo to see it larger, swipe for more
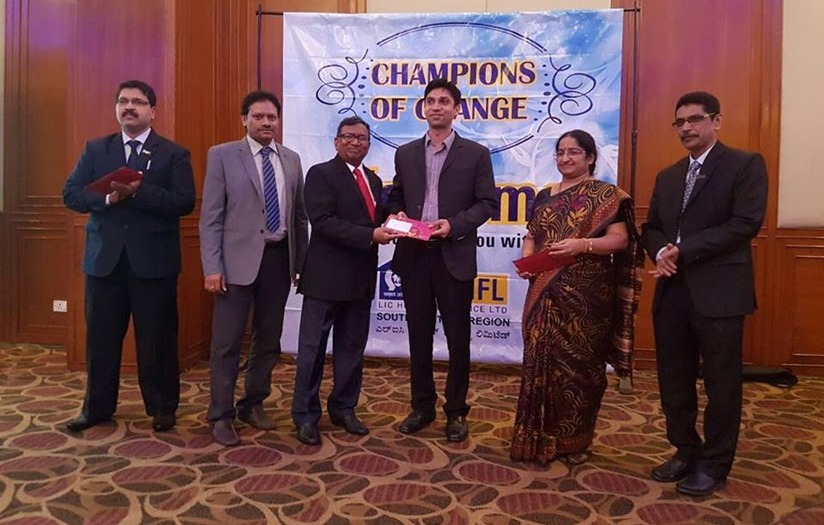
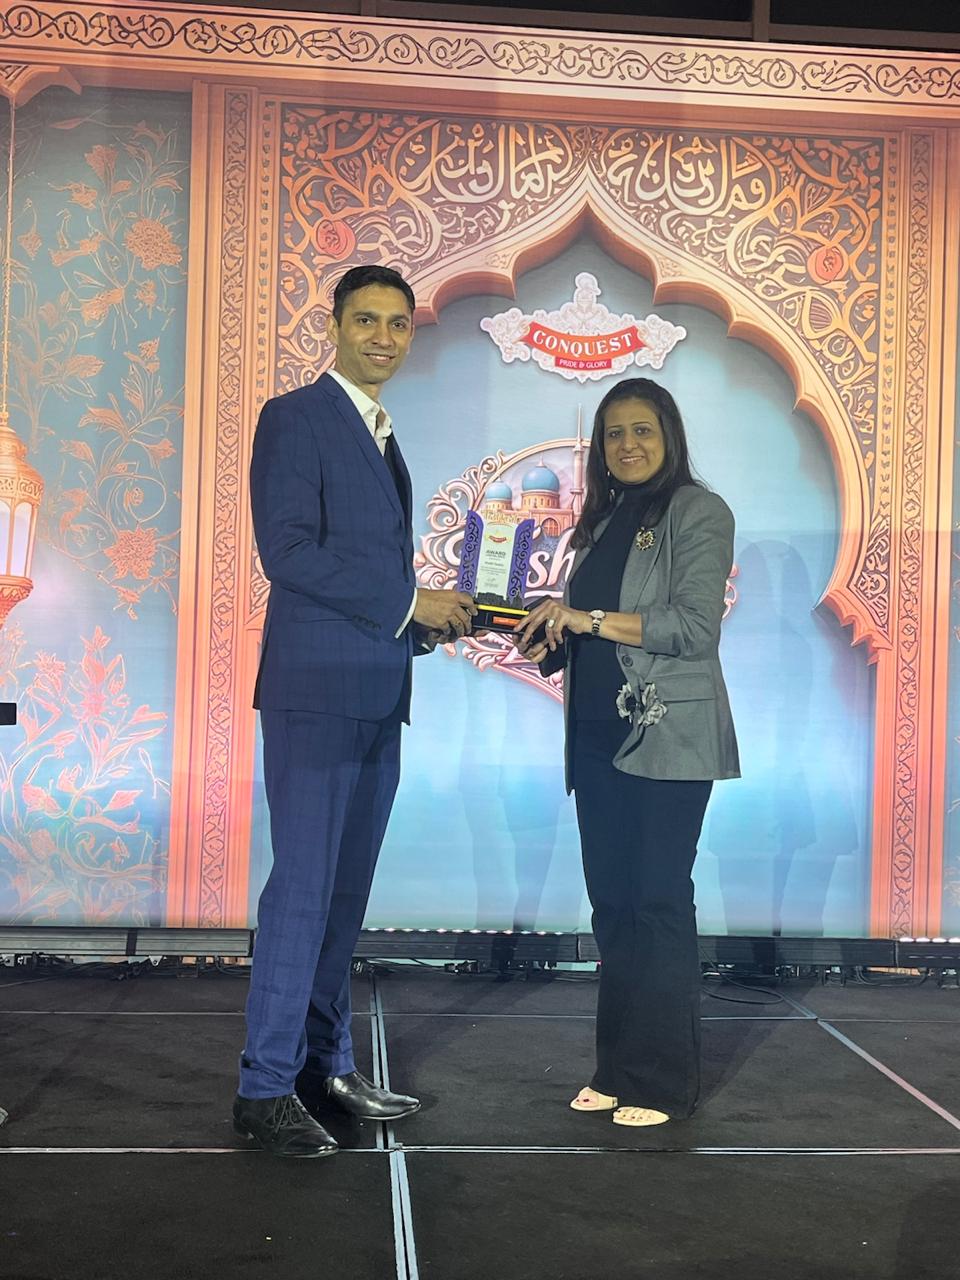
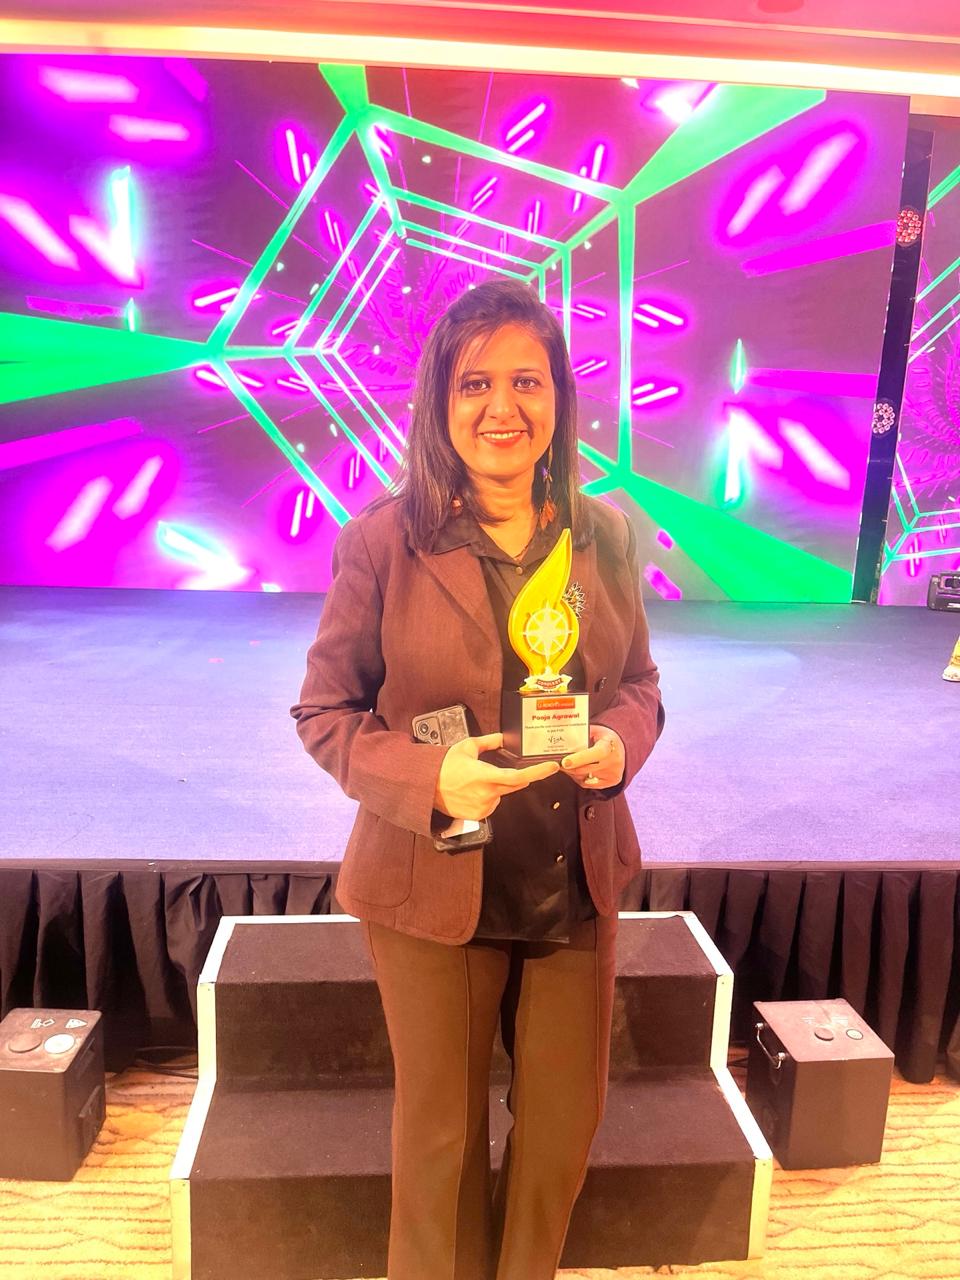
Our process
The home loan process in Bangalore, in four stages. Here is what you do, what we do and what you get at each one.
Fill the short form, call or WhatsApp. Our expert calls you back during office hours.
We look at your income, credit and property papers, and tell you honestly what is possible.
We shortlist lenders that suit your property, compare rates and charges with you, then prepare and submit your file.
We coordinate the lender's legal and valuation checks, and stay with you until the money is released and the property is registered.
Move the sliders to see your monthly EMI, total interest and total payment. It’s a quick estimate; your lender’s figures may differ slightly.
Monthly EMI
₹43,391 per month
Want to know how much you can actually borrow?
Check my eligibility for freeResults are estimates for illustration only and are not a loan offer.
Google reviews
Questions we hear every day
Straight answers on Khata, documents, fees and timelines. If yours isn't here, just ask.
Still have a question?
Call or WhatsApp our expert. It's free, and there's no obligation.
Open all 7 days, 10 AM – 7 PM
Often, yes. One bank's “no” usually reflects that bank's own policy, not every lender's. Some banks, NBFCs and housing finance companies do lend on B Khata properties, usually with stricter document checks and sometimes a lower loan amount or a slightly higher rate than for an A Khata property. Whether a lender will consider yours depends on the title, the layout, the construction and your income. Share your details and we'll tell you honestly which lenders may consider it.
B Khata means the property is entered in the city's tax records but has deviations or approvals pending, such as an unapproved layout or building plan. It lets you pay property tax, but it is not the same as full approval, and it does not by itself prove clear title. Before you buy, have a property lawyer check the title and documents; the lender's lawyer will also do their own check. We can explain what lenders look for, but we don't give legal opinions.
A Khata is for properties that meet the city's building and layout rules. B Khata is for properties that are in the tax records but have deviations or pending approvals. E Khata is the digital Khata issued through the government's online system; it is a format, and it shows whether the property is A or B Khata. Since 2025, Bengaluru's city administration has moved from BBMP to the Greater Bengaluru Authority and five city corporations. Rules change from time to time, so we check your papers against the current requirements.
For most properties within Bengaluru city limits, the sub‑registrar's office asks for an e‑Khata at registration, and lenders ask for it too. If you don't have one yet, apply early, because it can take time. We'll tell you what your chosen lender needs for your property.
It depends on your property and your timeline. Conversion can widen your choice of lenders, but it has costs and takes time, and the government's conversion schemes have had their own rules on eligibility, fees and deadlines (for example, the 2025 scheme covered sites but not flats). If you need the loan soon, a lender that accepts B Khata may be the practical route. We'll go through both options with you.
No. Our advice and file support carry no fee for borrowers: no consultation fee and no file charge. Lenders still charge their own processing, legal and valuation fees, and we tell you about these before you apply. We are a home loan advisor, not a lender, so the final decision on your loan is always the lender's.
It depends on the lender, your documents and the property. Loans on B Khata, E Khata and other Khata properties usually take a little longer, because the lender's legal and technical checks are more detailed. Once we've seen your papers, we'll give you a realistic timeline for your case.
Every case is a little different, so we give you a checklist for yours.
More answers on our FAQ page
Still have a question?
Call or WhatsApp our expert. It's free, and there's no obligation.
Open all 7 days, 10 AM – 7 PM
Tell us about your property and your loan. Our expert will tell you which lenders suit your case and what you may be able to borrow, with no obligation.
Open all 7 days, 10 AM – 7 PM
No. 62, The High Street, Jayanagar 4th BlockGet directions (opens Google Maps in a new tab)